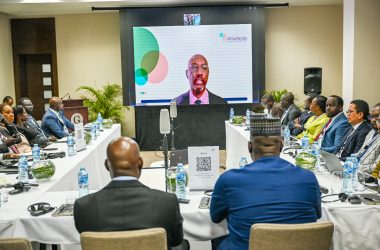
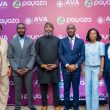

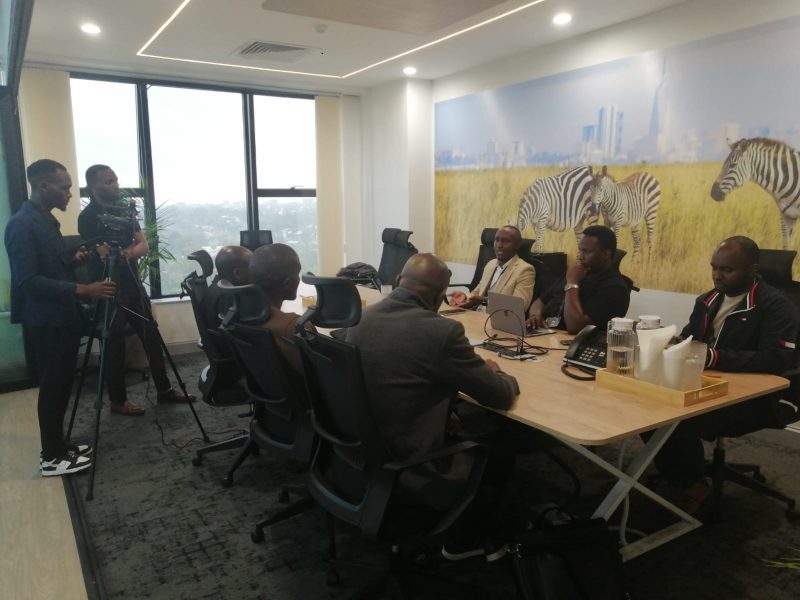
Kenya’s payments market is at an inflection point. Mobile money drove mass adoption over the past decade, but rising trade volumes and regional expansion are exposing limits in the underlying rails. Faster settlement, clearer FX pricing and tighter system integration are now front and centre. That shift formed the basis of a Nairobi roundtable hosted by Verto.
Kenya built its reputation on consumer payments. Businesses now want more.
As companies expand into Uganda, Tanzania and beyond, they are running into delays, multiple intermediaries and patchy reconciliation across banks and wallets. Cross-border transfers often mean layered fees and opaque foreign exchange spreads. For SMEs, that can tie up working capital for days.
Mark Mwaniki, Verto’s Kenya sales director, said the pressure is coming from firms operating at scale.
“Kenya has proven what is possible when innovation meets strong demand, but the conversation now needs to shift to infrastructure,” Mwaniki said. “Businesses want payments that move as fast as their operations do. That means fewer intermediaries, clearer pricing, and systems that can handle both local and cross-border transactions without friction.”
Participants said the problem is not basic transfers. It is what sits behind them. Real-time settlement. FX management. Reconciliation across channels.
Many firms still manage payments through a mix of banks, mobile money and international platforms. That fragmentation adds cost and risk. For exporters and importers, even small FX margins can erode thin profit lines.
The discussion turned to infrastructure. Not new apps, but the systems that connect local methods to global networks.
Mwaniki argued the goal is to link what already works. “It’s about connecting systems so money can move efficiently and transparently across markets,” he said.
Regulation came up too. Industry players called for clearer rules and ongoing dialogue between the Central Bank, commercial banks and fintechs. Without that, firms may hesitate to invest in deeper integrations.
Kenya positions itself as a regional business hub. That ambition depends less on front-end features and more on whether its core payment systems can handle larger, more complex flows.
The next phase will test whether the country can move from consumer scale to infrastructure depth.